
 AU · AUD
BPAY casinos Australia: biller claims, availability and risks
Australian source-based guide · 18+
Evidence note: This is a public-source review, not a deposit or withdrawal test. Casino references are not recommendations. A login provider or payment logo does not make an online casino legal to offer services in Australia.
| Claim | Evidence status | Reader implication |
|---|---|---|
| BPAY operates through Australian banks | Supported by Australian Payments Plus | A genuine domestic bill-payment service |
| A particular casino accepts BPAY | Not verified here | Do not infer acceptance from a logo |
| Casino deposits arrive in a fixed time | No transaction evidence | No casino timing guarantee published |
| BPAY can receive casino winnings | Not established | A separate payout route would need evidence |
| A BPAY logo proves Australian licensing | Incorrect inference | Payment and gambling permission are separate |
Public-source evidence only. No casino payments were made and no specific casino biller was verified. Provider availability must not be interpreted as casino acceptance.
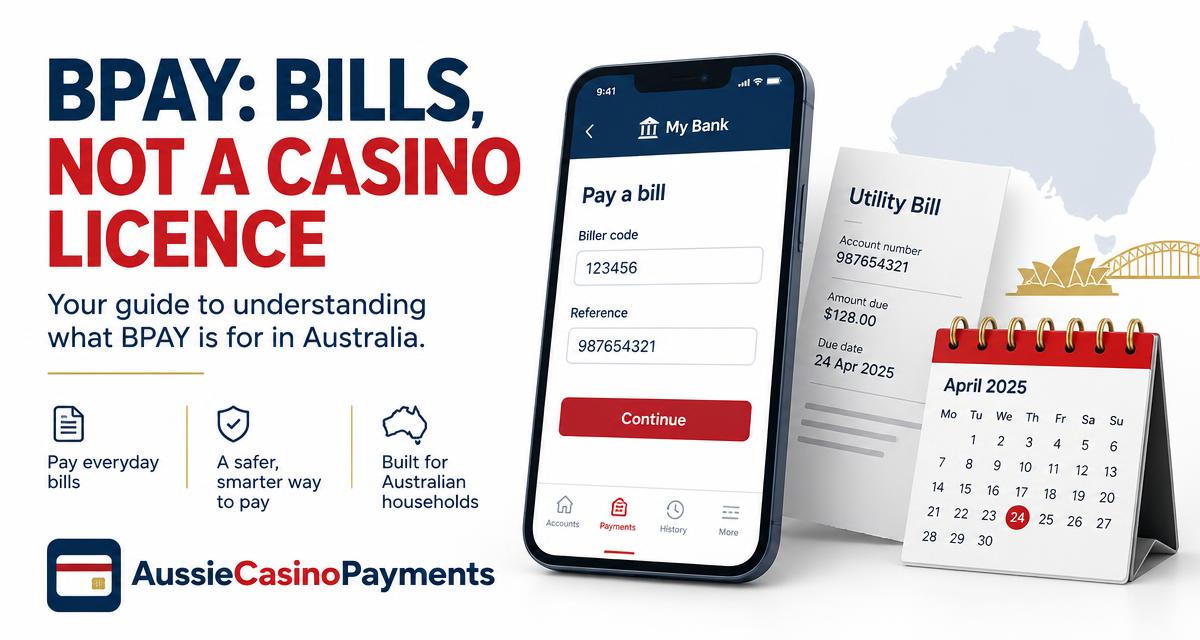
BPAY casinos Australia is a search phrase, not proof of an available Australian casino deposit service. BPAY is a familiar way to pay a bill through online banking. That familiarity can make a casino cashier claim look more reassuring than the evidence warrants. This guide explains the payment system without turning an unverified biller claim into a recommendation.
BPAY was already listed in our payment catalogue, but it did not have a dedicated published article. This page closes that gap with a public-source review. We have not sent money to a casino biller, confirmed a current casino Biller Code or measured a BPAY casino deposit. There is no top-five ranking because this review cannot substantiate five eligible Australian casino billers.
The provider’s Australian Payments Plus BPAY overview describes a bill-payment service available through more than 140 financial institutions. It uses a Biller Code and Customer Reference Number. Those facts support a guide to how BPAY works. They do not establish acceptance at a particular offshore gambling website.
For other banking concepts, compare our PayID casinos guide and the payment methods hub. For account access rather than money movement, the Inclave casinos guide explains a common category mistake: a login service is not a deposit method, just as a payment brand is not an operator licence.
Can Australians actually use BPAY at an online casino?
We did not establish a current, eligible BPAY casino biller in this review. That is a narrower statement than claiming none could ever exist. It means the evidence available here is insufficient to recommend an operator, publish its biller details or tell readers that a payment will be accepted from their bank account.
Australian availability of BPAY itself is not the same as availability at a casino. The bank must support the service, the recipient must be an eligible participating biller and the particular payment must satisfy applicable conditions. A logo pasted into a cashier is not confirmation of all three. Nor is an old comparison article repeating a deposit option.
There is also a legal question before the banking one. ACMA identifies online casino services offered to Australians as prohibited under the Interactive Gambling Act. A genuine payment destination would not change that. We do not provide casino Biller Codes or funding instructions because there is no verified, lawful Australian casino shortlist behind this page.
No worries about paying the electricity bill does not translate into no worries about a casino balance. The familiar bank screen proves that you are using your banking service. It does not prove that the recipient will credit an account, honour a payout or come under Australian gambling supervision.
How an ordinary BPAY bill payment works
An ordinary BPAY payment identifies a participating biller through a Biller Code. A Customer Reference Number tells that biller which customer or account the payment concerns. The payer submits the payment through their financial institution’s supported banking service. These identifiers serve different purposes and should not be treated as interchangeable.
The code is not a general bank account number. The reference is not a password or a one-time security code. A reference can be specific to the biller and customer, and a valid-looking sequence does not prove that the money will be allocated to the intended account. Check the underlying bill and recipient information through trusted channels.
The bank’s interface may show a biller name before confirmation. Read it. A name that does not match the expected recipient is a reason to pause, not a minor inconvenience. We do not advise readers to ignore mismatches or use a third-party biller to conceal the purpose of a transaction.
After submitting a legitimate bill payment, retain the bank’s receipt and reference. Those records help the financial institution and biller trace a payment. A receipt confirms what was submitted through the bank; it does not necessarily prove that a separate merchant account has already been updated.
For a household bill, the process is normally supported by an invoice and an identifiable customer relationship. A casino payment claim may lack those ordinary checks. Do not replace them with a screenshot supplied by a support agent whose identity you have not verified. The stronger the claim, the stronger the evidence should be.
Biller Codes, customer references and recipient checks
A Biller Code directs a payment to a participating organisation. The Customer Reference Number gives the recipient the information needed to allocate it. An error in either can create a different problem. The first can affect the destination; the second can affect which customer account receives the credit.
Do not copy payment details from a forum, a stranger’s message or another person’s account screenshot. The details may be old, wrong or specific to that person. Even if a bank accepts the format, that acceptance is not a guarantee that the intended recipient has authorised the arrangement.
A biller name can be a legal entity rather than the consumer-facing brand. That can happen in legitimate billing relationships, but the relationship should be explainable and documented. In a casino context, an unexplained intermediary is not something this guide treats as harmless. It adds another party whose role and obligations may be unclear.
A changed reference or a new destination deserves a fresh check. Scam messages often exploit a familiar brand to redirect payments. Use the contact details on an independently obtained bill or official website rather than replying to the person announcing the change. Do not send a small trial payment to an unverified casino as a substitute for evidence.
Keep security credentials separate from payment identifiers. A bank password, authentication code or recovery phrase should never be included with a biller inquiry. If someone asks for those details to verify a payment, stop. Tracing a bill payment does not require handing a stranger control over online banking.
Banking cut-offs, weekends and merchant crediting
BPAY is not a promise of instant casino credit. Payment processing depends on the financial institution’s conditions, submission time and biller arrangements. The time a banking app records the instruction can differ from the time the recipient receives information and from the time a merchant updates its own customer balance.
We do not publish a universal casino deposit time because no casino payments were tested here. A broad estimate copied from another website would create a false level of precision. For a legitimate bill, ask the bank and biller about their current timing rules and the effective payment date rather than assuming an advertising phrase applies.
Cut-off times and business days matter. A scheduled instruction, a weekend submission and a public holiday can each affect the practical timeline. Read the financial institution’s current guidance. A deadline expressed in one Australian time zone may not match the local clock where you are sitting.
In November, some Australian states observe daylight saving and others do not. Sydney time and Perth time are not interchangeable. We make no claim that a particular bank uses one universal cut-off across every account and payment type. The relevant source is the bank’s own current terms.
A missing merchant balance does not automatically prove a failed bank transfer. Equally, a completed banking instruction does not guarantee a valid merchant deposit. Record the amount in AUD, submission date, biller details and receipt number so a legitimate inquiry can distinguish processing, allocation and recipient problems.
Fees and limits: what can be stated honestly
This review does not establish a BPAY casino minimum deposit, maximum deposit or operator fee. Those figures would require a verified biller relationship and current terms. The A$5 or A$10 amounts advertised elsewhere on a gambling website should not be imported into a BPAY table without confirming they apply to the actual payment route.
Financial institutions can have account conditions, transaction limits and payment restrictions. A biller can also have its own conditions for accepting and allocating payments. Read both. A generic claim that BPAY is free everywhere overlooks the fact that the payer’s banking arrangement and any third-party service can have separate pricing.
Currency needs its own check. BPAY is an Australian bill-payment service, but that does not prove a separate gambling account settles entirely in AUD. A merchant can display an Australian-dollar balance while other contractual or accounting arrangements exist. Without documentation, we do not estimate an exchange spread or claim there is none.
Some services let customers pay bills through a separate app or intermediary. Any fee advertised by that service belongs to its own arrangement and is not automatically a fee charged by BPAY itself. This distinction also applies to acceptance rules: one app’s restricted biller categories do not establish universal scheme-wide rules.
The A$5 deposit guide and A$10 deposit guide discuss small amounts, not verified BPAY casino eligibility. A fiver is still money, and a small transfer can expose account details or encourage further deposits. Low value is not a substitute for a legitimate recipient.
Why a BPAY payment is not a casino withdrawal method
The ordinary BPAY flow is a payment from a customer to a participating biller. That does not establish a service for returning casino winnings to the customer. A website saying BPAY accepted may therefore be describing only an incoming payment option, even if the claim itself is accurate.
A refund, a correction of a payment and a gambling withdrawal are different events. Do not assume they follow the same process or have the same entitlement. If an operator mentions an alternative return method, that method needs its own current terms, identity requirements and legal assessment.
We publish no BPAY casino payout average. The fast payout casinos article concerns withdrawal claims and timing, but its figures are not evidence that BPAY receives winnings. The top payout article concerns game returns, which is another separate subject entirely.
A request for an extra deposit before a balance can be released deserves scrutiny. There is no evidence in this review that BPAY requires an unlocking transfer to release casino winnings. Preserve the message and contact the appropriate service independently. Do not let the promise of a larger payout justify sending more money to an uncertain recipient.
The safest editorial conclusion is simple: no withdrawal route has been established here. We state that gap instead of borrowing a bank-transfer estimate. A clear unknown is more useful than an attractive time range that applies to a different service and a different account relationship.
Bank and app restrictions are not all the same
We did not find official evidence establishing a universal BPAY rule that prohibits every gambling-related payment. That does not mean every gambling payment is permitted. Scheme participation, bank conditions, merchant eligibility and legislation are separate layers, and a restriction at any relevant layer can matter.
For example, Sniip’s biller review information describes restrictions on internet-gambling and casino billers within its own screening arrangements. That is evidence about Sniip and its banking partners. It must not be rewritten as a blanket official BPAY ban or as permission to use a different channel.
A financial institution may decline or restrict a payment for reasons specific to the account or recipient. Contact the institution through its official support route if an ordinary bill payment is declined. We do not offer techniques for hiding merchant categories, relabelling gambling transfers or routing around a protective banking control.
Card-funded gambling rules are also a separate question. Our Visa guide and Mastercard guide concern card networks and issuer conditions. Their conclusions cannot simply be pasted into a BPAY bank-payment guide. The source must match the payment arrangement being discussed.
If an online source makes an absolute claim, ask whose rule it is quoting. Is it the payment scheme, the bank, an intermediary app, a merchant or the regulator? Identifying that owner often resolves apparent contradictions. One service can reject a biller without proving that the entire national payment system has the same rule.
Australian casino law does not change with the payment logo
ACMA’s Interactive Gambling Act guidance identifies online casinos as services that cannot be offered to people in Australia. BPAY does not issue gambling licences and its brand is not evidence of one. The domestic origin of a payment service does not make every recipient a lawful Australian gambling operator.
ACMA’s consumer warning about illegal operators is relevant to accessible offshore websites. Availability on a phone does not establish legality or Australian consumer protection. An Australian-dollar display, local slang or an Australian flag can make a website look local without proving its regulatory status.
We explain restrictions on providers rather than asserting that merely reading a casino page is an offence for an Australian reader. That distinction is not a recommendation to participate. Offshore disputes can be difficult, and a payment receipt does not create gambling regulator oversight where it does not exist.
These are national online-casino concerns, not a loophole that changes between NSW, Victoria, Queensland or Western Australia. Local time, a bank branch address or the state selected in an account form does not alter the service category. Check authoritative Australian guidance rather than a casino support agent’s reassurance.
What to do if an ordinary BPAY payment goes wrong
Contact your financial institution promptly through an official channel. Explain whether the concern is an incorrect biller, an incorrect customer reference, an unauthorised payment or an expected biller credit that has not appeared. Those categories can require different investigations. Do not describe every problem as a chargeback.
BPAY does not automatically provide the same dispute mechanism as a card-network purchase. Your rights and the correction process depend on the banking arrangement and the circumstances. We do not guarantee a reversal, reimbursement or recovery deadline. Ask the bank for the relevant process and a written case reference.
Keep the receipt, amount, date, biller name and reference. For a merchant inquiry, provide only the information necessary to trace the payment. Do not post a complete bank statement in a public forum. If screenshots contain account identifiers or personal details, consider redaction before sharing them with anyone other than an appropriately verified service.
If you suspect a scam, stop further payments and contact the bank immediately. Someone offering guaranteed recovery for an upfront fee may be attempting a second scam. A failed or disputed transfer is not a reason to install remote-access software or disclose authentication codes to an unsolicited caller.
BPAY, PayID and Inclave solve different problems
BPAY identifies a biller and customer reference within a bill-payment service. PayID identifies an eligible account using a linked identifier, such as an email address or mobile number. Inclave concerns account access. These names sometimes appear together on gambling websites, but they are not substitutes for one another.
The PayID guide should not be read as a BPAY timing test. A feature of an instant account transfer does not establish a feature of biller processing. Likewise, the Inclave guide does not describe a way to send or receive money, regardless of how quickly a login completes.
Wallets add another relationship. Our MiFinity article discusses a wallet category, while PayPal has its own service and acceptance conditions. Neither category should be used as evidence that a BPAY biller is available or that the same dispute rights apply.
The right comparison separates purpose, evidence and recourse. What does the service do? Which specific recipient has been verified? What terms apply if something goes wrong? Those questions are more valuable than ranking unrelated brand names by a generic fast-and-safe label.
| Service | Core role | Does not establish |
|---|---|---|
| BPAY | Pay participating billers through banking | Casino eligibility or a winnings return route |
| PayID | Identify an account for supported transfers | Merchant legality or an operator guarantee |
| Inclave | Manage credentials and account access | Deposit acceptance or withdrawal speed |
| Card or wallet | Use a separate payment service | Universal casino support or identical dispute rights |
Our evidence standard and update policy
This article was prepared from public sources on 3 November 2026. The date records an editorial source review. It does not imply that casino accounts were funded or that timing measurements were repeated. We identify those limits near the top so readers do not need to find them buried in a footnote.
The primary service description comes from Australian Payments Plus. The Australian legal baseline comes from ACMA. The intermediary restriction example comes from Sniip and is attributed only to that arrangement. We have not created a casino-acceptance list from unsourced marketing claims or assumed that existing casino cards establish current BPAY support.
Our how we test guide describes the wider testing topic. For this article, no numeric casino benchmark is available. If stronger evidence becomes available, it must establish the recipient, conditions and relevance to Australian residents before a deposit figure can be considered meaningful.
Corrections can be sent through the contact page. Include the exact statement and a current authoritative source. Please do not send account passwords, banking security codes or identity documents. The editorial team page identifies the site’s credited roles; a byline is not a substitute for the evidence behind a claim.
For Australian readers, the takeaway is not to search harder for a workaround. It is to recognise where the evidence stops. BPAY is a real Australian bill-payment service. A verified, lawful Australian online-casino biller and a tested casino payment journey are not established by this guide. Those are different statements, and keeping them separate is the point.
Frequently asked questions
Are BPAY casinos available in Australia?
This review did not establish a current eligible casino biller. Australian availability of BPAY itself does not prove casino acceptance, and online casino services cannot legally be offered to Australians.
What details does an ordinary BPAY payment require?
A participating Biller Code and a Customer Reference Number, submitted through a supported financial institution. Verify the recipient and reference using trusted billing information.
How fast is a BPAY casino deposit?
No casino deposit was tested for this guide, so no reliable casino time is published. Ordinary bill-payment timing depends on the bank, submission time and biller arrangements.
Can BPAY receive casino withdrawals?
No such route was established here. An ordinary BPAY payment sends money to a biller; a winnings payout requires separately verified arrangements.
Does BPAY ban all gambling payments?
The official sources reviewed did not establish a universal scheme-wide prohibition. Banks, intermediary services and biller eligibility rules can impose separate restrictions; this is not permission to pay an offshore casino.
Is a BPAY logo proof of an Australian casino licence?
No. Payment branding and gambling authorisation are separate. Refer to ACMA’s guidance on the Interactive Gambling Act.
Can I reverse a mistaken BPAY payment?
Contact your bank promptly. The investigation and any remedy depend on the circumstances and banking terms; a reversal or card-style chargeback is not guaranteed.
Is Inclave another name for BPAY?
No. Inclave is described as a login and password-management service. BPAY is a bill-payment service. Neither brand establishes casino legality.
18+ only. Feeling like gambling isn't fun any more? Call Gambling Help Online on 1800 858 858 or visit gamblinghelponline.org.au. You can block yourself from every licensed Australian wagering provider through BetStop.
Written and fact-checked by
Author
Payments editor
Nadia spent nine years in Australian retail banking operations, including four on real-time payments rollouts, before moving into consumer payments journalism. She runs our deposit and withdrawal test bench.
- New Payments Platform
- PayID
- Card scheme rules
- Chargebacks
Fact-checker
Compliance fact-checker
Tom is a former AML analyst who checks every claim we publish against ACMA guidance, the Interactive Gambling Act 2001 and current state regulator positions before it goes live.
- Interactive Gambling Act 2001
- ACMA enforcement
- AML/CTF
- Responsible gambling codes
Every page is written by one editor and independently verified by another — see our editorial team.